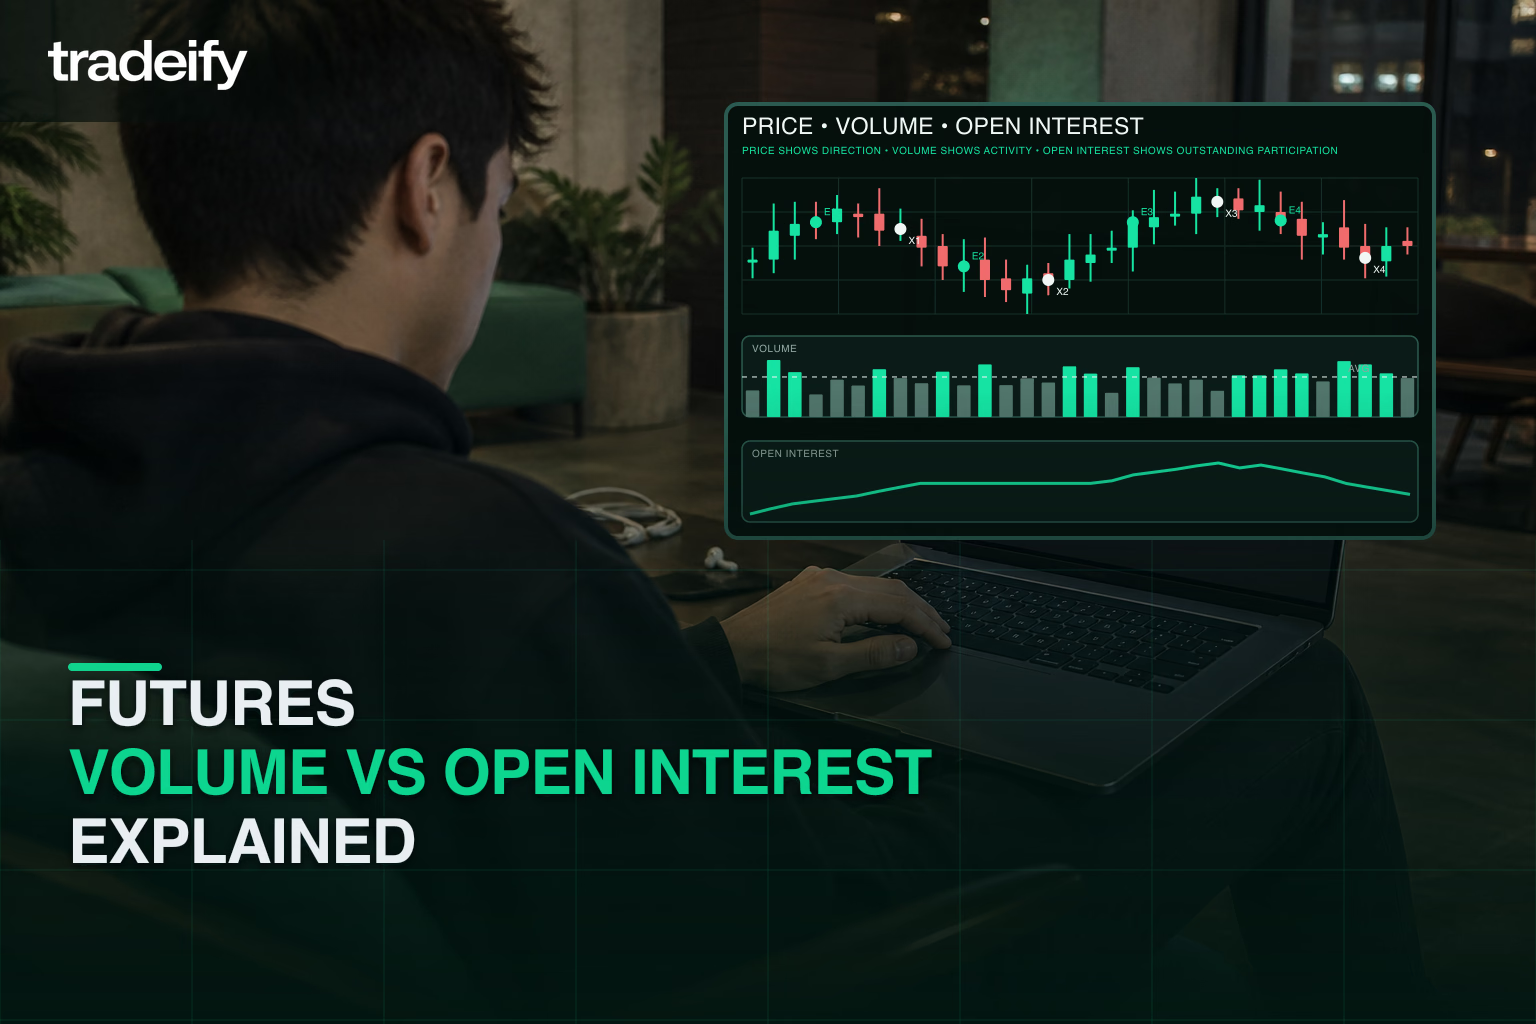




TL;DR: A COT report chart shows how groups of traders are positioned in futures markets. The CFTC generally releases Friday reports using Tuesday positions, so the chart provides delayed positioning context rather than an intraday entry signal. Compare net positions, changes in gross longs and shorts, and open interest within the same report category. Keep the contract, report type, and lookback consistent before deciding whether positioning is unusually stretched.
Price is pushing higher, but the positioning chart shows large traders reducing exposure. Do you trust the breakout or expect a reversal?
A COT report chart cannot settle that decision by itself. It can help you ask a better question: is the move attracting new positioning, losing participation, or continuing despite a crowded trade?
The useful part is the context. The costly mistake is treating a weekly positioning number like a real-time buy or sell instruction.
What a COT report chart actually shows
The Commitments of Traders report groups positions by trader classification. It reports open interest, meaning contracts that remain open, rather than the number of trades completed that week.
The CFTC’s report guide explains the main report families. Legacy reports use commercial and noncommercial classifications. Disaggregated reports separate physical-commodity participants into more specific groups. Traders in Financial Futures reports use categories such as asset managers and leveraged funds.
Those labels describe business classifications, not whether a trader is right. A commercial participant can hold a position for reasons that are very different from your directional trade.
You also need to distinguish futures-only data from futures-and-options-combined data. Switching between them halfway through a comparison changes what you are measuring.
Where to find a COT report chart
Start with the original CFTC report to confirm the market and report date. For visual comparison, CME Group’s Commitment of Traders tool provides a chart-based way to examine positioning.
A useful chart should let you identify:
- The exact futures market and report family.
- Whether the series includes options.
- Long positions, short positions, and net positioning.
- The reporting date and historical lookback.
- Open interest or positioning as a percentage of open interest.
Do not assume two chart providers use the same defaults. One may show total contracts while another shows an index scaled between historical extremes. Similar-looking lines can describe different quantities.
For your first review, choose one market and one report family. Add complexity only after you can explain what each line measures.
How to read net positions on a COT chart
Net positioning is long positions minus short positions for the selected group. A positive number means the group has more longs than shorts in that report. A negative number means the reverse.
Consider this hypothetical change:
- Previous week: 120,000 longs and 80,000 shorts, producing a net long position of 40,000.
- Current week: 115,000 longs and 60,000 shorts, producing a net long position of 55,000.
The net line rose by 15,000 contracts. Yet the group reduced its long positions. The stronger net reading came from a larger reduction in shorts.
That distinction matters. Fresh long buying and short covering can both make the net line rise, but they tell different stories about participation. Review the components before describing the change as aggressive buying.
Now imagine open interest also fell. That would add another reason to avoid calling the move an expansion of broad market participation without further evidence.
Put COT positioning extremes in context
An extreme reading needs a comparison window. The largest net long position in six months may be ordinary in a five-year history.
Some charts use a COT index. A common construction places the current net position between the lowest and highest readings in a selected lookback. A reading near the upper end means positioning is close to that window’s high, not that price has a matching probability of falling.
Before using an extreme, record the lookback and ask three questions:
- Has the market’s size changed enough that raw contract counts are misleading?
- Does the same extreme appear when positioning is divided by open interest?
- Has price previously continued trending while this group stayed heavily positioned?
Crowding can persist. A strong trend does not owe you a reversal because a positioning indicator reached its upper band.
Calculate a COT index before interpreting its extremes
A common COT index is 100 × (current net position − lowest net position) ÷ (highest net position − lowest net position), using the same trader group and lookback throughout.
Suppose that group’s net position ranges from -20,000 to 80,000 contracts over your chosen window and currently stands at 60,000. The index is 100 × 80,000 ÷ 100,000 = 80. That means the current position is 80% of the way from the window’s minimum to its maximum. It does not mean 80% of traders are long or that a reversal has an 80% probability.
If the highest and lowest values are identical, the denominator is zero and this formula is undefined. Changing from a 26-week to a 52-week window can also change the reading without any new position being opened. Keep the raw net-position chart beside the index so the normalization does not hide the actual exposure.
Use a COT chart without forcing an entry
Keep weekly context separate from your execution rules. A practical review can follow this sequence:
- Confirm when the data was measured and when it became available.
- Describe the net change and its long-versus-short components.
- Compare that change with price behavior over the same reporting period.
- Write a conditional scenario for the coming session.
- Wait for your independently defined entry and invalidation criteria.
For example, a hypothetical market may be near a previous weekly high while net longs remain elevated. Your observation is crowded positioning near resistance. Your condition might be a failed breakout followed by acceptance back inside the prior range.
If price instead holds above that range and your failure condition never appears, the short setup has not triggered. The COT observation does not replace it.
COT chart mistakes that distort the signal
The release lag is the first limitation. Friday’s report generally describes Tuesday positions. A major move between those points may already have changed exposure. Holidays can also alter the release schedule.
Another mistake is treating all markets identically. Positioning in an agricultural contract and positioning in an equity-index future can reflect different participants and business needs.
Historical testing has its own trap. If a backtest assigns Tuesday’s report to Tuesday’s trades, it may use information that was not public yet. Align any signal with its actual release availability.
Finally, avoid selecting a lookback only because it makes the current chart support your view. Record the settings before evaluating the trade, then keep them consistent.
Build one repeatable COT chart review
Save a chart with the report type, date, net position, gross position changes, and open interest visible. Write one sentence describing what changed and another describing what price action would make that context useful.
That creates a review you can revisit without rewriting the story after the outcome. COT data can improve your understanding of participation, but it cannot guarantee direction or protect a leveraged futures position from loss.