

TL;DR: Evaluate a trading strategy with net expectancy, payoff ratio, profit factor, drawdown, recovery time, and risk-adjusted returns, supported by sample size and realistic costs. A 40% win rate with $300 average wins and $150 average losses has a hypothetical $30 gross expectancy per trade before fees, a 2.0 payoff ratio, a profit factor near 1.33, and a breakeven win rate near 34.7% after $6 of costs per trade. Metrics should explain different parts of the same return stream. No single score proves profitability, account suitability, or future performance.
The strategy wins most of the time. That sounds encouraging until one loss erases several winners.
Another strategy wins less often but keeps losses controlled and lets a smaller number of winners pay for them. Comparing the two requires more than a win-rate screenshot.
Trading strategy performance metrics should show how the strategy makes money, what it costs to execute, and what losses you must survive along the way. Start with the trade records, then calculate the numbers consistently.
Define the trading performance sample first
Decide what counts as a trade and whether partial exits belong to one complete position. Use the same convention across strategies.
Record the market, dates, session, position sizing, and whether results are backtested, simulated, or live. Separate deposits and withdrawals from trading results.
Include commissions and execution costs. If slippage is modeled rather than observed, label the assumption and test a less favorable case.
Platforms calculate some metrics differently. TradesViz’s Sortino documentation is one example of a provider publishing its method. Read equivalent definitions for the platform producing your own report, especially before comparing its figures with another tool.
Calculate expectancy from wins and losses
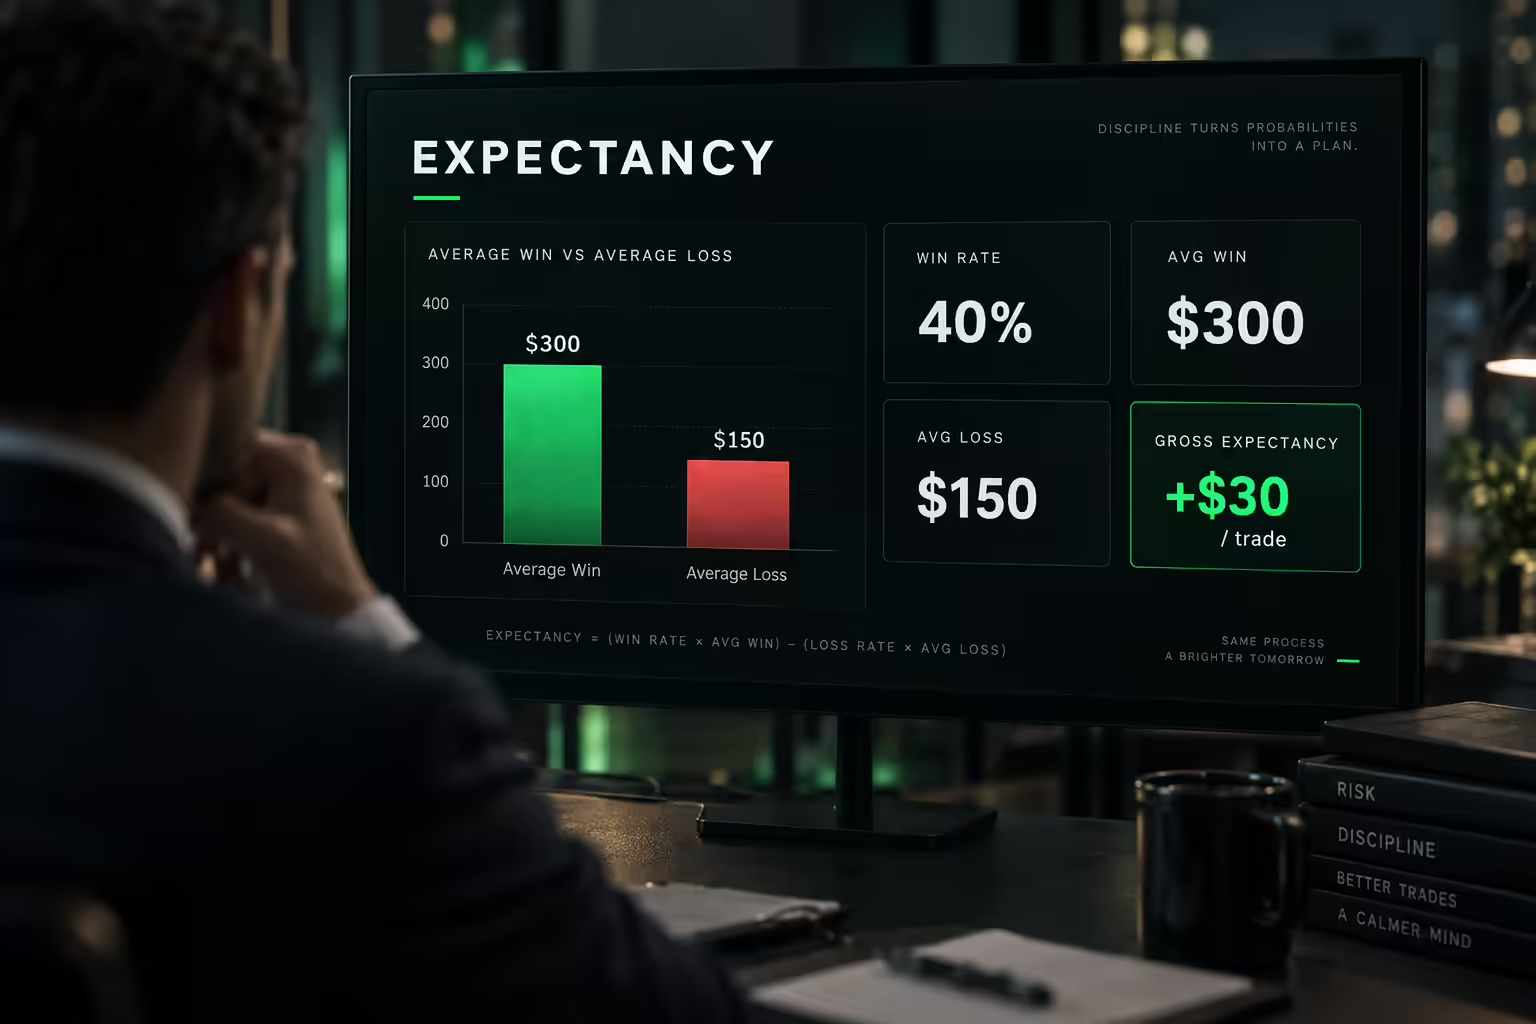
Expectancy estimates average profit or loss per trade in the measured sample. A simple gross version is:
Expectancy = Win rate × Average win − Loss rate × Average loss
Treat average loss as a positive magnitude in this formula. Then subtract average costs if they are not already included in the win and loss figures.
In a hypothetical sample, a 40% win rate, $300 average win, and $150 average loss produce $120 − $90 = $30 gross expectancy per trade. With $6 in average costs, net expectancy becomes $24.
That result is a sample estimate. It does not mean every trade is worth $24 or that the next hundred trades will reproduce the average.
Break the sample into meaningful segments. An attractive overall average may hide a setup that performs poorly in the session you actually trade.
Read payoff ratio and profit factor together
Payoff ratio is average win divided by average loss. In the example above, it is 2.0. That describes the relative size of outcomes, not how frequently they occur.
Profit factor is gross profit divided by the absolute value of gross loss. With forty $300 winners and sixty $150 losers, gross profit is $12,000 and gross loss is $9,000, producing a profit factor of about 1.33 before costs.
Be explicit about cost treatment. Some platforms report profit factor from net trade results, while others present separate cost lines.
Do not read an extremely large profit factor from a tiny sample as strong evidence. One large winner and very few losses can produce an impressive ratio that changes sharply with the next trade.
Add breakeven win rate and R-multiples
Breakeven win rate connects outcome size to the frequency of wins required. With fixed illustrative average wins of $300, losses of $150, and $6 of cost on every trade, the breakeven rate is ($150 + $6) ÷ ($300 + $150), or about 34.67%. The formula assumes those outcome sizes and costs remain stable; a live sample rarely matches them exactly.
An R-multiple expresses a trade’s result relative to its initial planned dollar risk. If initial risk is $100 and the net outcome is +$180, the result is +1.8R. A -$120 net loss is -1.2R, making a loss beyond the original plan visible.
Use the initial risk recorded before entry, not a denominator chosen afterward. Dollar expectancy measures the account’s realized economics; expectancy in R helps compare trades taken at different planned risk levels. They can tell different stories when size changes, so retain both instead of using normalized results to conceal large dollar losses.
Measure drawdown and time to recovery
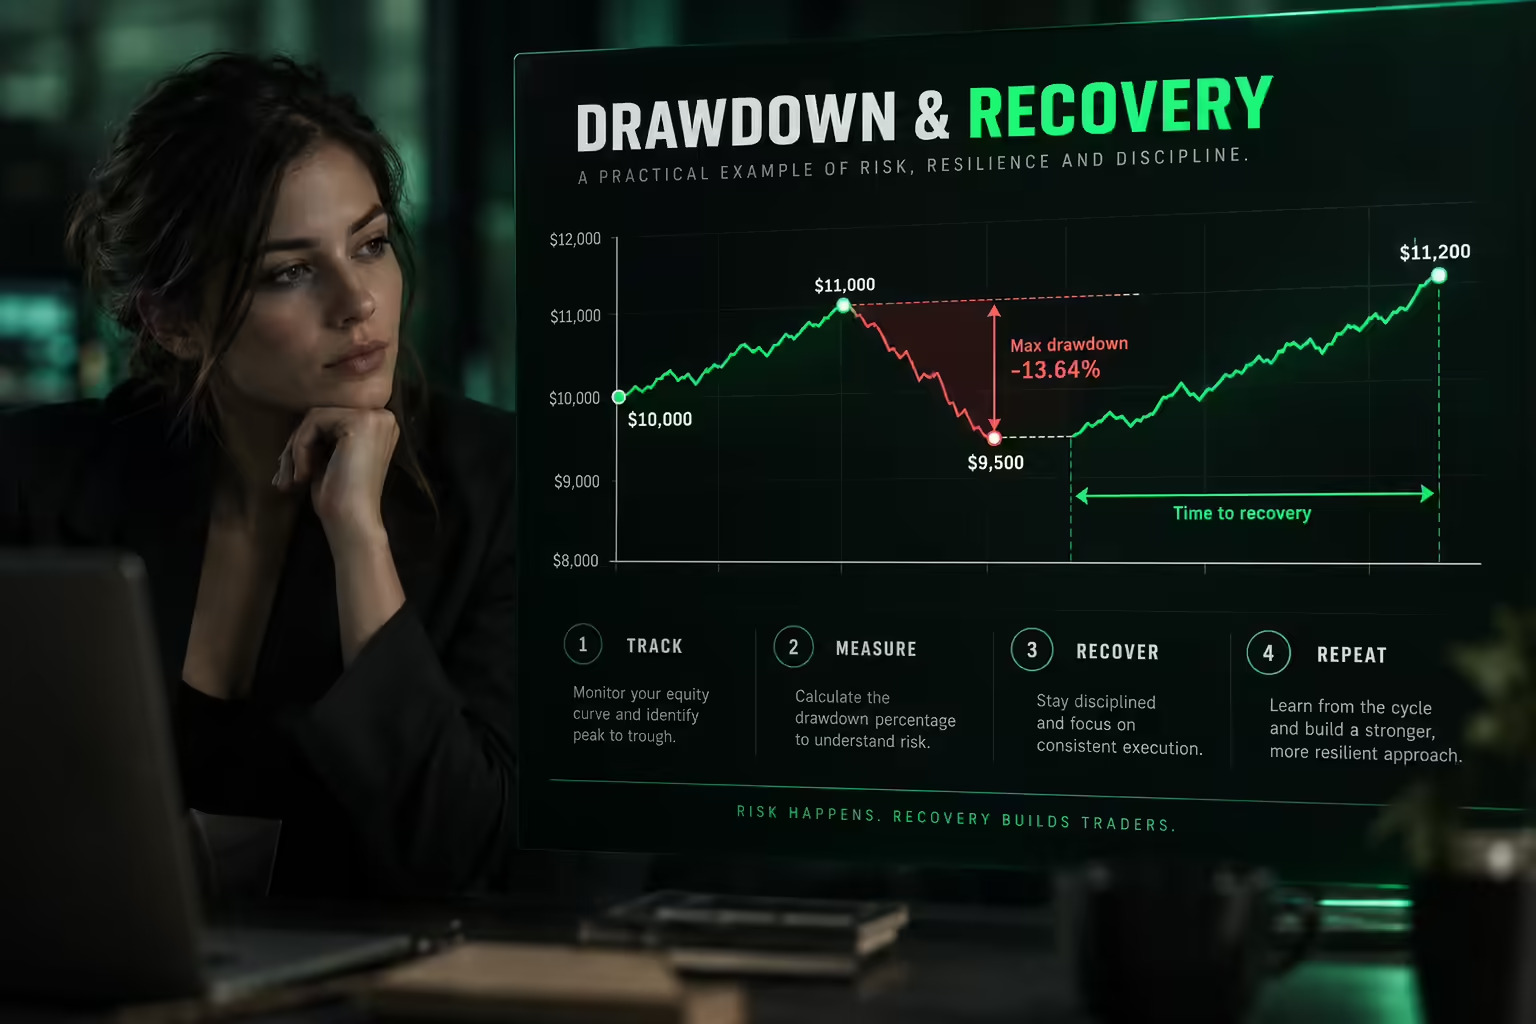
Maximum drawdown describes the largest peak-to-trough decline in the selected equity series. The observation frequency matters: an intraday equity curve can show losses that daily closing balances hide.
Consider a hypothetical equity path from $10,000 to $11,000, down to $9,500, then up to $11,200. The largest decline from the prior peak is $1,500, or approximately 13.64% of $11,000.
Recovery time asks how long the strategy took to exceed the previous peak. Two strategies can have similar drawdowns but very different periods spent below their highs.
For a prop account, also model the program’s actual failure threshold. A historical strategy can finish profitably while crossing a real-time account boundary along the way. End-of-day performance alone will not establish that the account would have survived.
Use risk-adjusted performance metrics carefully
Sharpe compares excess return with overall return variability. Sortino focuses on shortfalls below a chosen target. Other ratios compare returns with drawdown.
Each answers a different question. None replaces a review of the largest losses or the account’s specific restrictions.
Use matching return frequency, target or risk-free assumptions, and annualization conventions. A daily unannualized ratio should not be compared directly with an annualized monthly ratio.
Be cautious when returns are dependent, highly skewed, or based on changing size. A strategy that earns small gains until a rare large loss may look attractive before the rare event occurs.
Track execution metrics beside returns
Performance can deteriorate because the strategy changed or because execution changed. Track both.
Useful execution measures include average slippage, rejected orders, missed fills, entry delay, rule adherence, and results by setup or session. Maximum adverse excursion and maximum favorable excursion can help examine what happened while a trade was open, provided the data is detailed enough.
Suppose gross expectancy is stable but net expectancy falls. Higher costs or worse fills may explain the change more directly than a new indicator setting.
If only discretionary trades outside the written plan are losing, separate that behavior from the strategy’s rule-compliant sample. Do not quietly remove the errors from your account-level results, however. They still cost real money.
Test trading performance beyond one good sample
Reserve data the strategy did not use during development. Avoid repeatedly adjusting rules until they fit the same history.
Review performance across market conditions, costs, and reasonable parameter changes. A strategy whose results collapse after a tiny adjustment deserves closer scrutiny.
Sample size matters, but there is no magic number that proves an edge. The diversity and independence of observations, the size of the estimated effect, and the strategy’s complexity all affect confidence.
Keep uncertainty visible. A range of plausible outcomes is often more useful for sizing decisions than a single optimized score.
Trading strategy performance metrics compared
The table below puts the hypothetical numbers from this guide in one place. Win rate is listed first because most reports start there, yet it answers only the frequency question.
| Metric | Formula | What it answers | Hypothetical example |
|---|---|---|---|
| Win rate | Winning trades ÷ total trades | How often trades win | 40% |
| Net expectancy | Win rate × average win − loss rate × average loss − average costs | Average result per trade after costs | $24 per trade |
| Payoff ratio | Average win ÷ average loss | How large wins are relative to losses | 2.0 |
| Profit factor | Gross profit ÷ absolute gross loss | How gross profits compare with gross losses | About 1.33 before costs |
| Breakeven win rate | (Average loss + cost) ÷ (average win + average loss) | Minimum win rate needed at current outcome sizes | About 34.7% |
| Maximum drawdown | Largest peak-to-trough decline ÷ prior peak | Worst decline from an equity high | About 13.64% |
| Recovery time | Time from the prior peak until equity exceeds it | How long capital stayed below a high | Depends on the equity path |
| Return to drawdown | Annualized return ÷ maximum drawdown | How much return the strategy earned for its worst decline | Depends on the period measured |
| Sharpe and Sortino ratios | Excess return ÷ return volatility, or ÷ downside deviation | Return per unit of variability or shortfall | Depends on return frequency |
Read the rows as a set. A 40% win rate looks weak on its own, but a 2.0 payoff ratio and a breakeven rate near 34.7% explain why the sample can still carry positive net expectancy.
Return-to-drawdown ratios, including MAR-style calculations, compare a strategy’s return with its worst decline. Use the same period and drawdown measurement for every strategy you compare.
Build a compact performance review
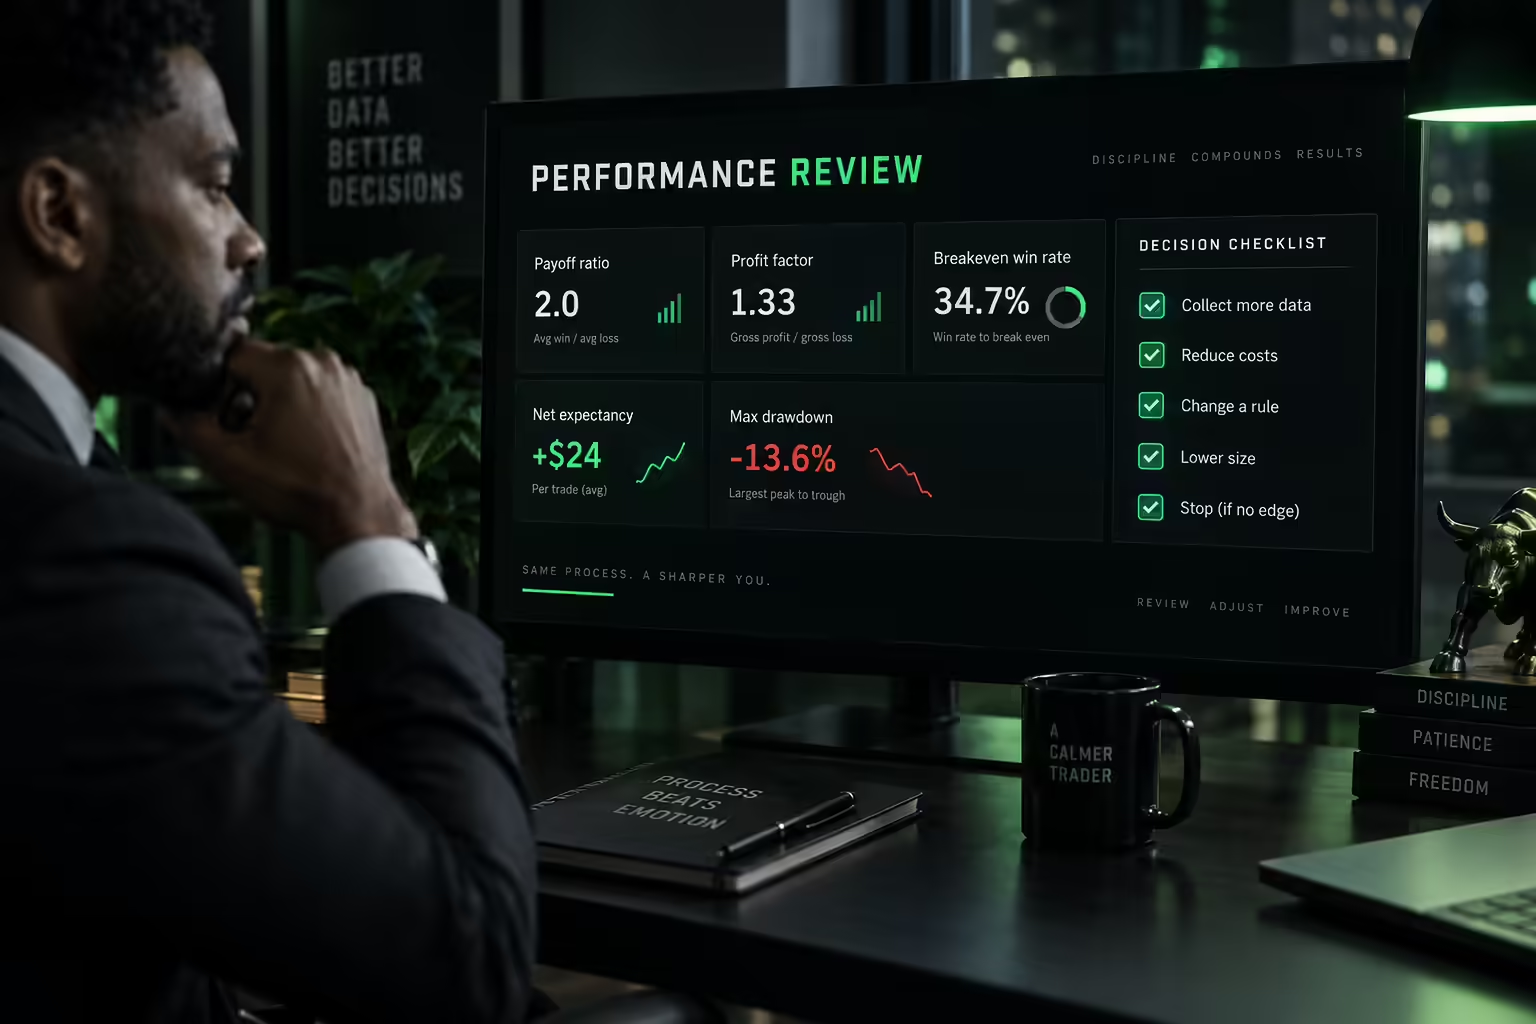
Start with net expectancy, payoff ratio, profit factor, maximum drawdown, recovery time, and sample description. Add only metrics that answer a specific unresolved question.
Then connect each number to a decision: whether to collect more data, reduce execution costs, change a rule, lower size, or stop using the strategy.
The purpose of performance metrics is to expose tradeoffs and weak assumptions. A dashboard should help you investigate the strategy, not give it a certificate of safety.
Frequently asked questions
What are 5 examples of metrics to measure performance?
Five useful trading strategy performance metrics are net expectancy, profit factor, payoff ratio, maximum drawdown, and recovery time. Together they show the average result per trade, how gross profits compare with gross losses, the relative size of wins and losses, the worst decline from a peak, and how long equity stayed below that peak. Add a risk-adjusted ratio such as Sharpe or Sortino when you compare return streams measured at the same frequency.
What trading strategy has a 90% win rate?
No strategy type reliably holds a 90% win rate across markets and time, and a high win rate says nothing about profit on its own. A strategy that wins 90% of the time with $50 average wins and $600 average losses has a negative expectancy of $15 per trade before costs. Check payoff ratio, expectancy, and the largest losses before trusting any high win rate.
Is win rate a good measure of trading strategy performance?
Win rate is useful but incomplete. It shows how often trades win, not how much winners earn or losers cost. A 40% win rate can be profitable with a 2.0 payoff ratio, while a 70% win rate can lose money if the average loss is much larger than the average win.
What is a good profit factor for a trading strategy?
A profit factor above 1.0 means gross profits exceeded gross losses in the sample, while a figure below 1.0 means the sample lost money. There is no universal target, because sample size, cost treatment, and drawdown all change what a given figure means. A hypothetical 40% win rate with a 2.0 payoff ratio produces a profit factor of about 1.33 before costs, which still needs testing on data the strategy has not seen.
How many trades do you need to evaluate a trading strategy?
No fixed number proves an edge. Confidence depends on how varied and independent the trades are, how large the estimated edge is, and how complex the rules are. Treat early results as a range of possible outcomes and keep collecting data before increasing size.